Join Groups & Channels, No Spamming

Morbi paper mills see full-capacity operations as ceramic industry revives; Kraft paper exports to China spike, Prices strengthen; Janmashtami shutdown ahead
The BE and caustic soda plant marks a key milestone for Mohit Paper Mills, enabling full utilization of installed capacity and enhancing overall production efficiency
Expert Views on the paper market scenario, How the West Asia Crisis Helped the Industry, MIP for WPP, Anti-Subsidy implementation, and paper price trends
Pudumjee Paper intends to develop new varieties addressing applications for stronger paper bags and cupcakes; Plans 68,000 MT Mahad Specialty Paper Facility within 5 years
India Paper Industry at an Inflection Point: War, Costs, and Capacity; Demand growth expected at 5–7% in FY26
“Surging exports of paper will most certainly keep the domestic prices quite high”: Mr. A. Annamalai, Director – RFC
The Status of the Global Container board Industry, Recycled Paper Demand and Supply and its impact on the Indian Industry
Akshay Jain, director of Silverton Pulp & Paper, says it's time to promote agro residue as a raw material to lessen the scarcity of fibre
Advantageously located, a new paper mill is all set to roll kraft paper in Madhya Pradesh
Several agile interventions helped ITC-PSPD fortify its clear leadership of the Value Added Paperboards (VAP) segment
Steeper-than-expected drop in realisations hits Seshasayee Paper’s FY2025–26 operating margins; Box boards, Absorption Kraft, and Virgin Kraft now form a growing share of the product mix
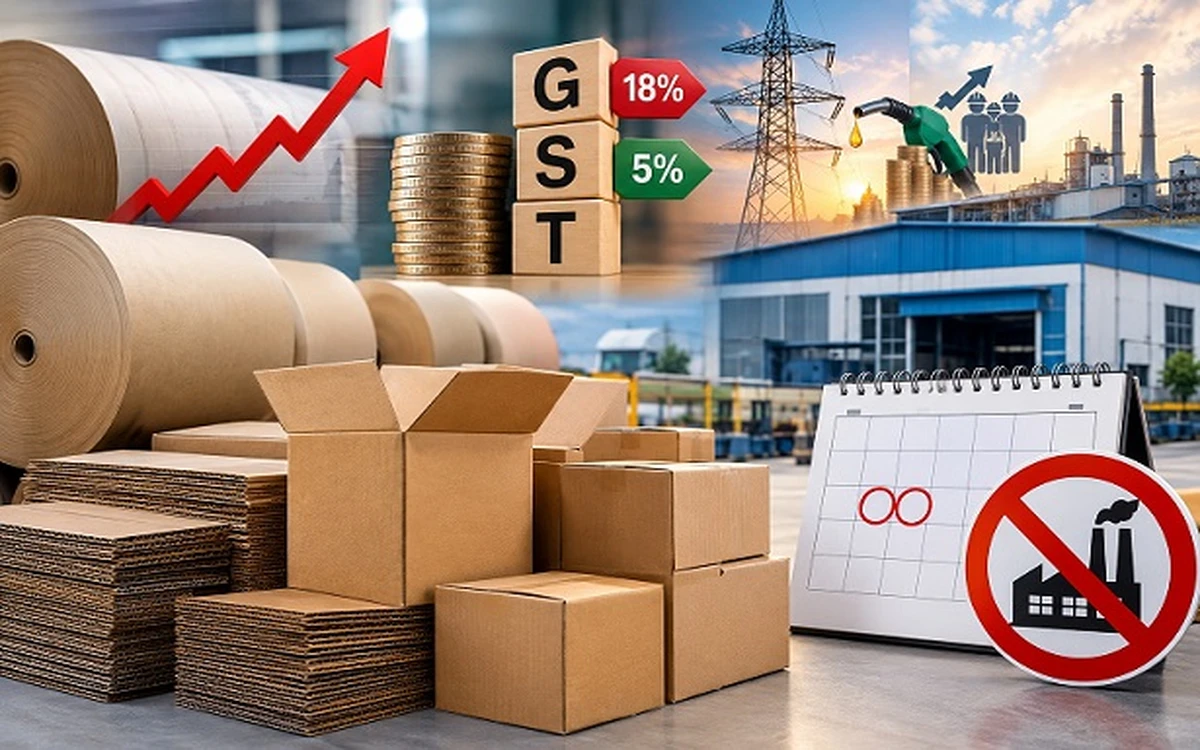
Overall Increase in Kraft Paper Prices Could Reach 35%; Industry Calls for 20% Box Price Increase, Voluntary Shutdown Proposed
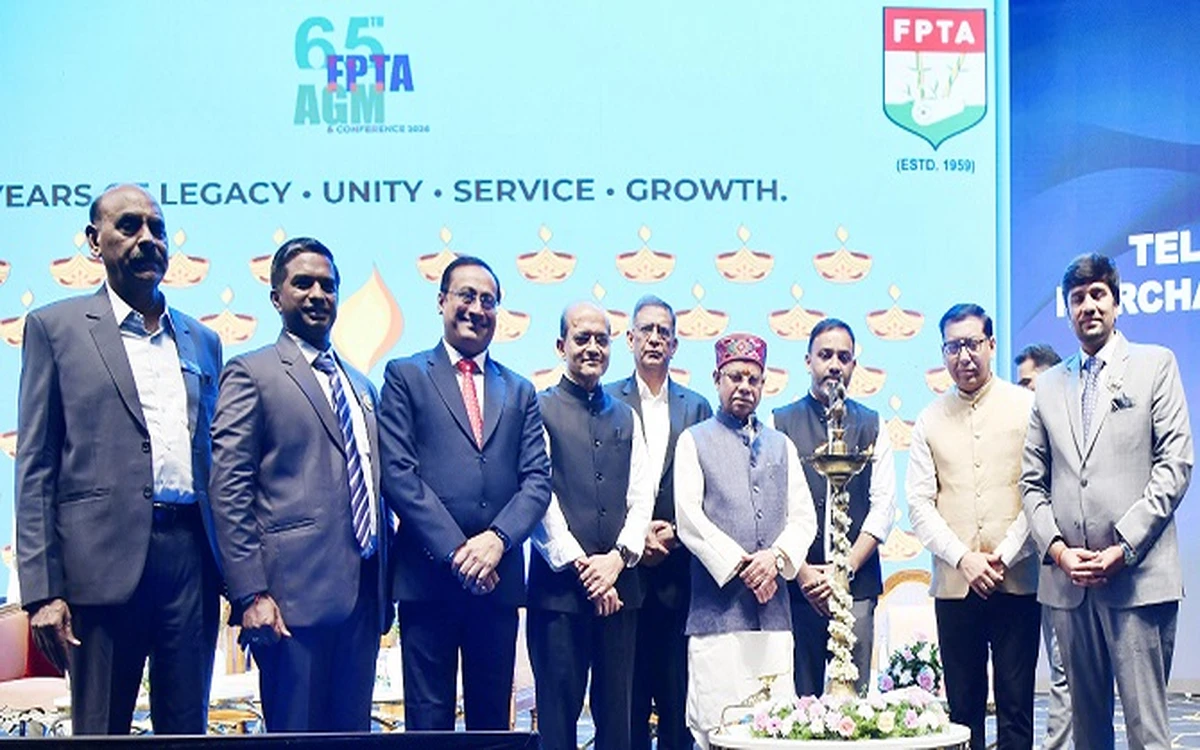
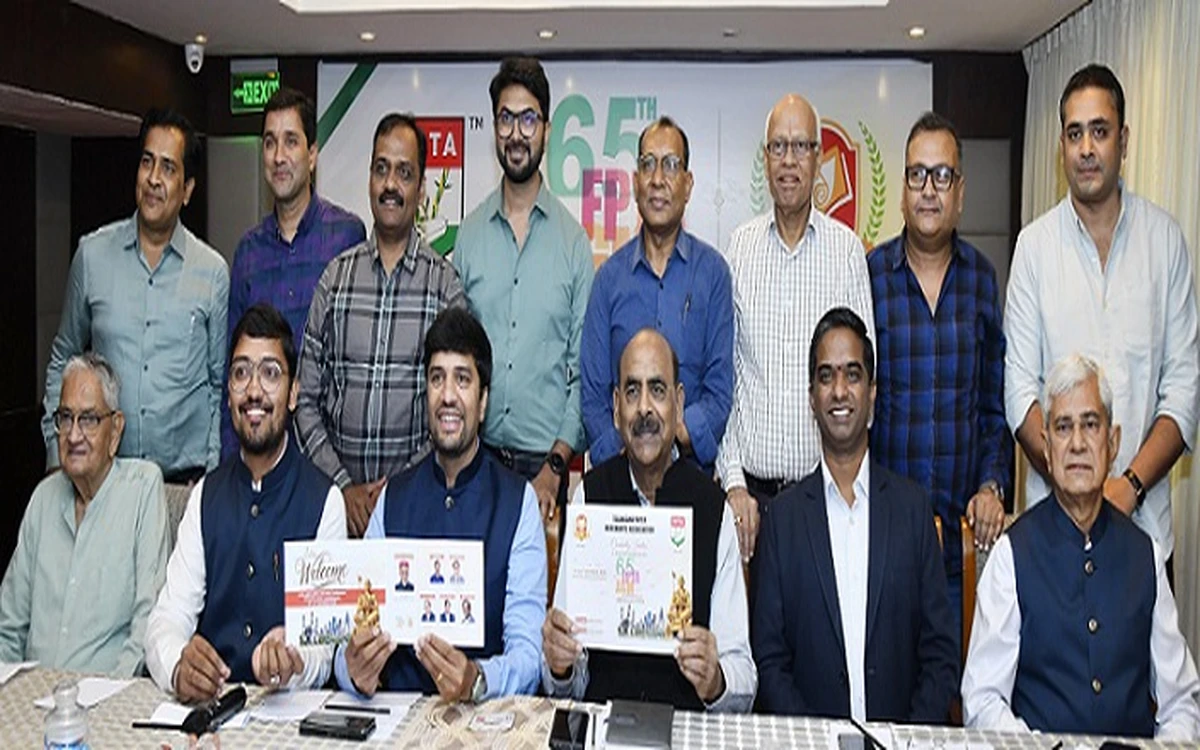
Paper Mills and Dealers Must Work Together to Create New Demand, Say Industry Leaders at FPTA’s 65th AGM
Ruchira Papers Invests a Sizeable Capex of Rs. 235–240 Crore Towards Writing & Printing Paper Capacity Expansion
Paper mills inflated the basic ex-mill price of paper post GST 2.0, AINMA seeks action against Anti-Profiteering
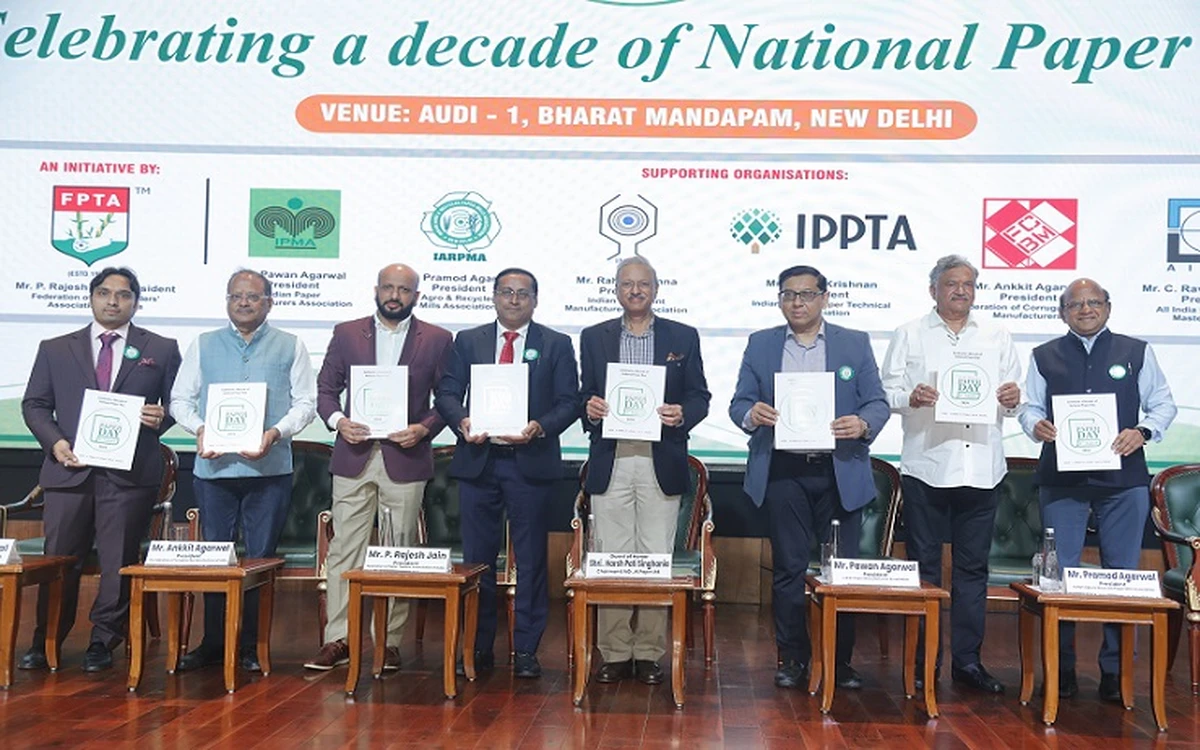
Seven Leading Associations Unite to Celebrate National Paper Day, Highlighting Paper's Sustainability and Circular Economy Advantage
Scientists from IIT-Guwahati develop India's first biodegradable plastic
Navneet Education focuses on brand building, curriculum-led growth, and export recovery; expects stationery margins to improve in FY27
It is estimated that USD10B to USD20B worth of single-use plastic packaging will convert to molded fiber, ZUME
Muzaffarnagar gets a new capacity of Tissue Paper and MG Poster paper
“The integration of digitalization, automation, and Artificial Intelligence (AI) is no longer a futuristic concept—it is the baseline for competitiveness in 2036” - Vinit Garg, Director, Vizen Solutions
DPIIT Report on the Paper Industry: Recent Expansions & Upgrades, Fastest-Growing Segments, and Total Operational Paper Mills in India
Overview of exports of select type of paper and key raw material used in the industry by Crisil Intelligence
Margin pressure pushes Pulp & Paper Packaging sector toward AI-Driven cost optimization, Cutting costs by 8–20%
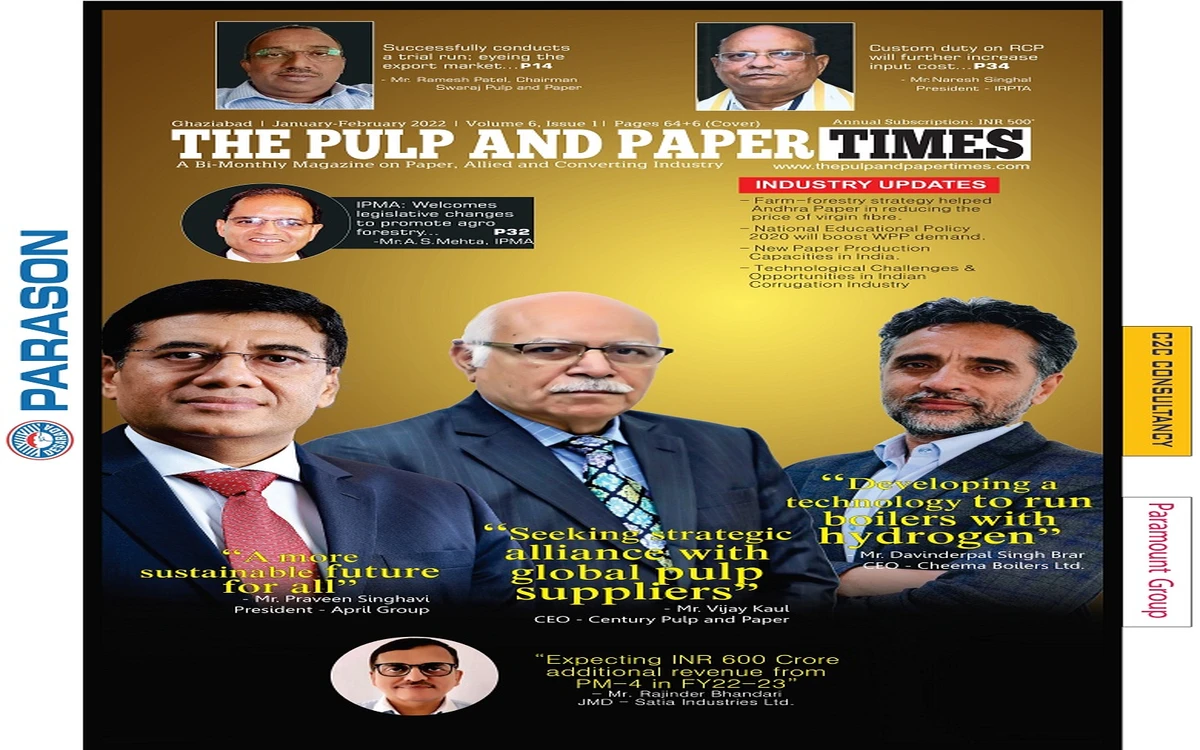
The Pulp and Paper Times Magazine : Volume 6, Issue 1
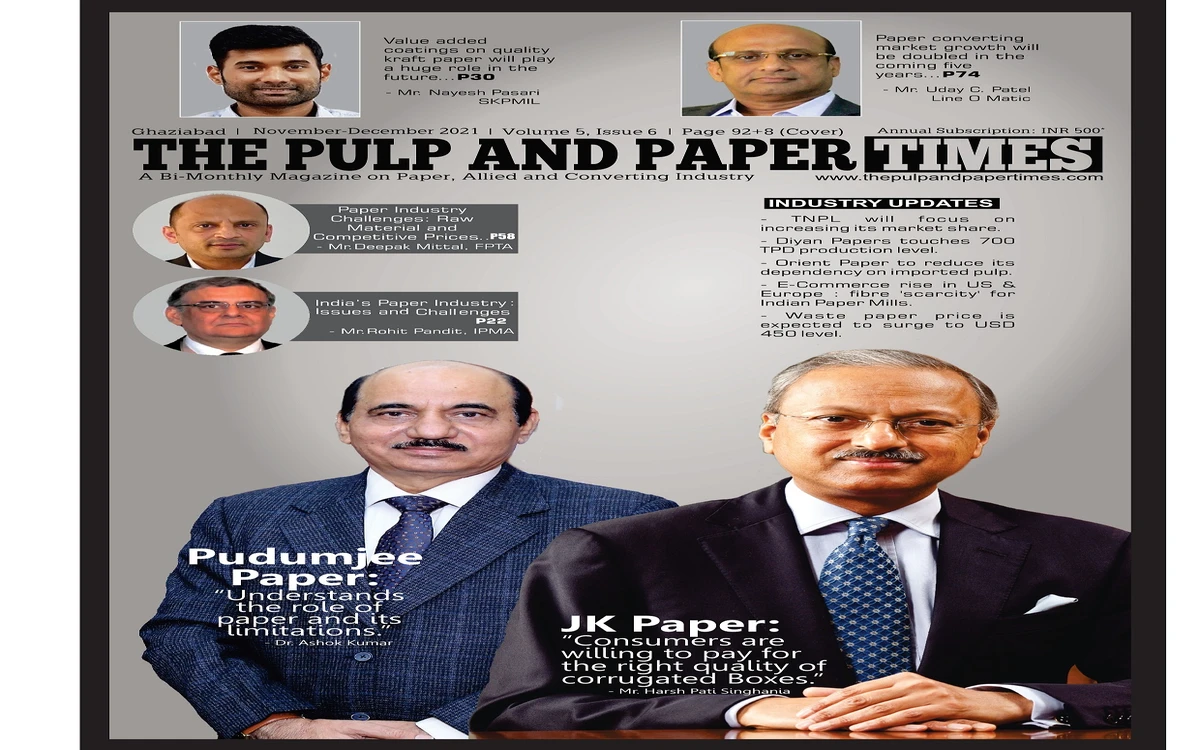
The Pulp and Paper Times Magazine : Volume 5, Issue 6
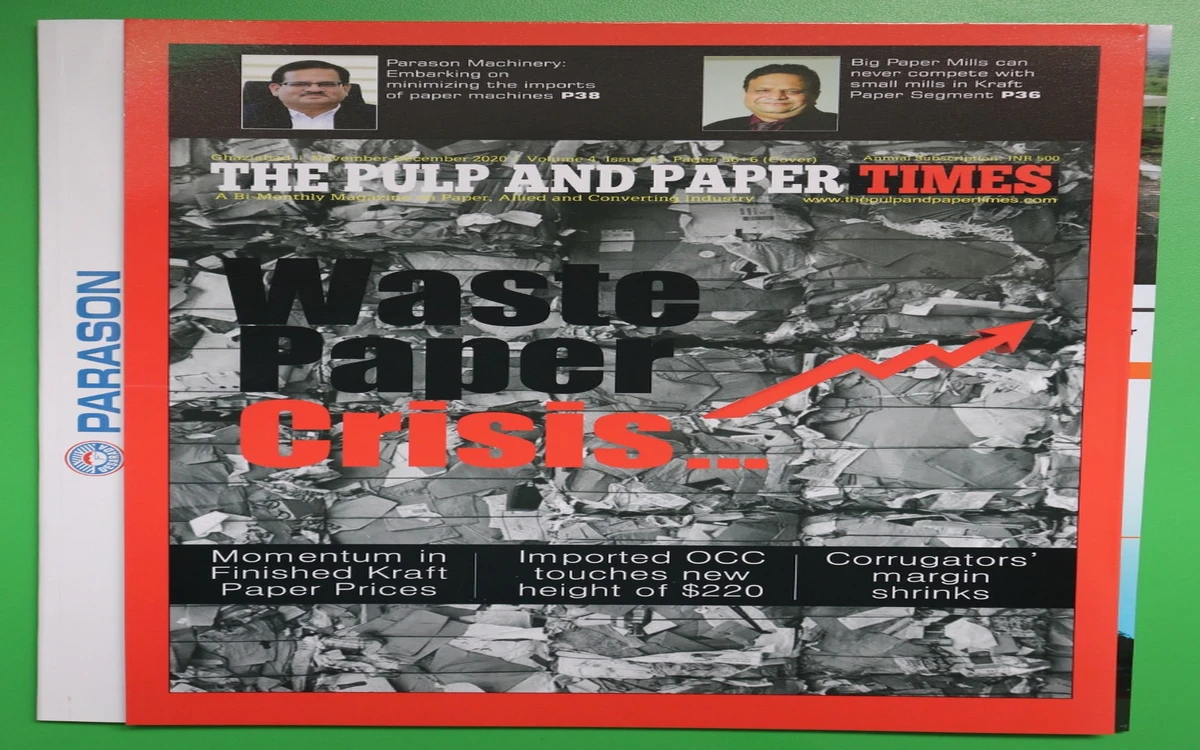
The Pulp and Paper Times: Volume 4, Issue 6
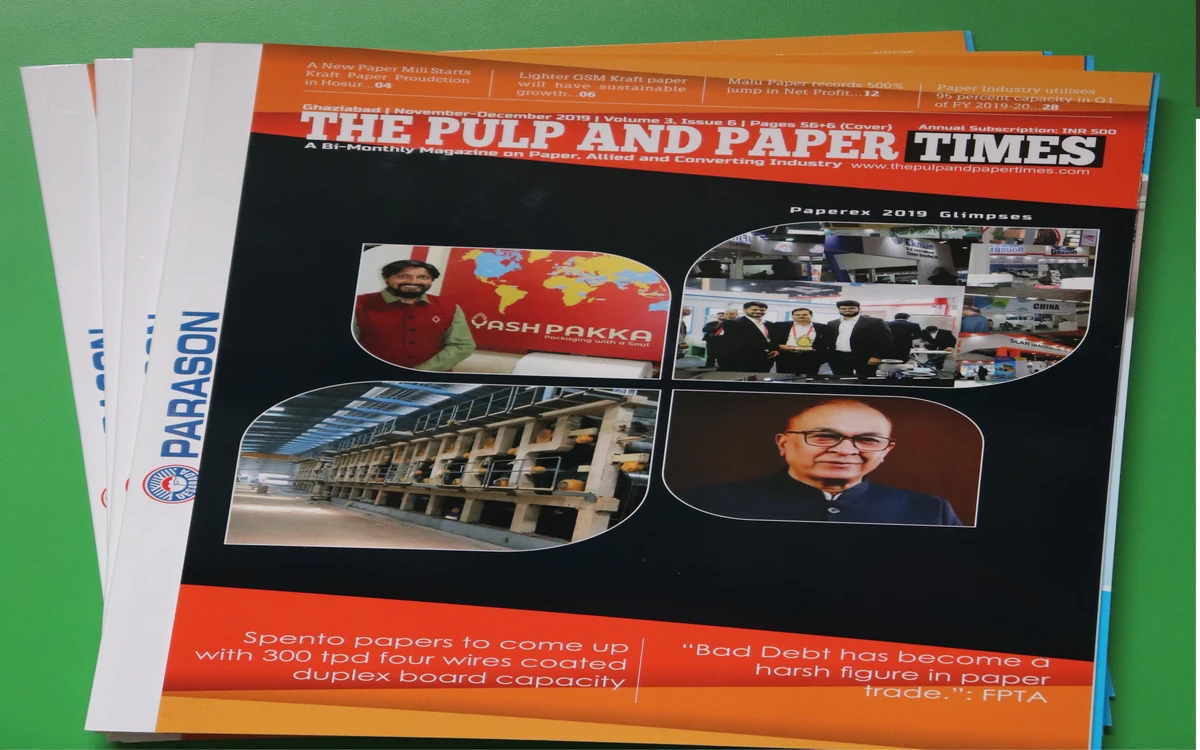
The Pulp and Paper Times : Volume 3, Issue 6
The Pulp and Paper Times: Volume 2 Issue 5
The Pulp and Paper Times, Volume 1, Issue 3
The Pulp and Paper Times, November 2016 Issue
The Pulp and Paper Times
Seshasayee Paper and Boards Limited (SPB), an Integrated Pulp, Paper and Paper board Mill, and the flagship company belonging to Writing and Printing paper manufacturing in India, has registered a fall in net profit during FY 2025-26 compared to corresponding period of previous year.
The fall in net profit during FY26 compared to the previous year is mainly due to lower average realisations per tonne of paper in both the Domestic & Export Market. Revenue from Operations of the Company for the year was Rs. 1710.17 crores, as against Rs. 1754.11 crores, in the previous year.
Accordingly, the impact of drop in realisations was much steeper than expected and the successful and significant cost reduction / optimisation efforts undertaken by the company could not offset the impact of drop in realisations in full. This has resulted in drop in operating margins during the FY26 as compared to FY 25.
As part of MDP III, Paper Machine 2 in Erode has been successfully modified to manufacture multi-layer boards, enabling production of cup-stock, carton board, and kraft liner board. The Company has developed in-house pulp-based Virgin Kraft packaging papers for the food industry, eligible for FSSAI certification. Box boards, Absorption Kraft, and Virgin Kraft now form a growing share of the product mix, reducing the Company's exposure to the secular decline in the P&W segment.
OPERATIONS:
The Company had registered the following landmarks during the FY 2025-26, in-spite of challenging market conditions.
-Highest ever annual production volumes at 2,48,385 tonnes.
-Highest ever annual sales volumes at 2,49,714 tonnes, with highest ever annual domestic sales volumes at 2,28,955 tonnes.
-Highest ever annual Production in Unit : Erode - 1,75,205 tonnes (Erode unit operating at 106% of the installed capacity).
During FY26, the production at Unit : Erode was 1,75,205 tonnes of paper, as compared to 1,70,426 tonnes, produced in the previous year, thanks to overall improved operations. (Average Capacity Utilisation stands at 106% in FY 26 in Unit-Erode).
SPB had completed project Mill Development Plan - III (MDP-III) in Unit : Erode in phases during FY 2020-21 and FY 2021-22. With the completion of Project MDP-III, the annual installed capacity of Paper for Unit : Erode stands augmented to 1,65,000 tonnes. The annual capacity of Unit : Tirunelveli remains at 90,000 tonnes. Accordingly, the total installed capacity of the company currently stands at 2,55,000 tonnes per annum.
Unit : Tirunelveli produced 73,180 tonnes of Paper during the FY26, as compared to 76,005 tonnes, produced in the previous year. (Capacity Utilisation at 81% in FY26 in Unit-Tirunelveli).
During FY26, company registered an overall sales of 2,49,714 tonnes of Paper (Previous year : 2,39,073 tonnes), with sales volumes growing by 4.5% in-spite of challenging market conditions.
The export volumes represented 8.4% of the production during FY26 (This stood at 11.6 % during FY25). The Company’s exports during FY26 was mainly affected due to disruptions to Exports to US in H1 of FY26 on account of the US Tariff related circumstances.
CURRENT YEAR (2026-27)
The margins for first and second quarter of FY 27 is expected to be affected by cost push on most imported and allied items (Pulp, Waste Paper, Chemicals, Coal, etc.) amidst the West Asia War crises. Paper mills are announcing price increases. But the effective implementation of the price increases will depend on the weakening of competition from Cheaper imports. Export business for the company is expected to be strong in FY27, provided the current levels of US tariffs remain.
Domestic market is expected to grow and will provide opportunities for growth for the company, thanks mainly to the wide product offerings by the company and the flexibility in altering product mix to suit dynamic and changing market conditions.
ENVIRONMENTAL PROTECTION
The Company continues to provide utmost attention to the conservation and improvement of the environment. In Unit : Erode, the Power Boilers, Lime kiln and Recovery Boilers are equipped with Electro Static Precipitators, to arrest dust emissions. The Company operates an Anaerobic Lagoon, for high BOD liquid effluents and a Secondary Treatment System, for total Mill effluent.
These facilities are operating efficiently, enabling the Company to comply with the Pollution Control norms, on a sustained basis. The treated effluent water continues to be utilised for irrigating nearby sugar cane fields. During FY 2025-26, the company, in its Erode unit, has installed and commissioned a Wet Electrostatic Precipitator (Wet ESP) in the existing Recovery Boiler to reduce particulate emissions from 100-120 Mg/nm3 to 40-45 Mg/nm3. This installation is the first of its kind in Indian Paper Industry.
The company had entered into Share Purchase Agreement and Energy Supply Agreement with the Indian Renewable Power generating company (SPV), during April & May 2025, for the purposes of developing a 52.8 MWp (DC) / 35.2 MW AC Solar Power Capacity and 9 MW Wind Power Capacity and intending to supply power to our company exclusively. The Solar / Wind power from the facility is expected to available for the company in Q-I of FY27.
MARKET CONDITIONS
FY 2025-26 was a transitional year for India's paper industry, marked by recovering demand, persistent import pressure, and global supply-chain volatility. Domestic demand continued to grow driven by e-commerce, FMCG, food delivery, the ban on single-use plastics and higher education spending, while the Union Budget's continued focus on manufacturing and MSMEs supported allied packaging demand. Cheaper Duty-free Imports from China and Indonesia continued to be the industry's biggest pain point. The pressure from cheaper imports got further accentuated with confusions arising out of GST 2.0 reforms announced in Sep’25, wherein the NIL GST on Paper for Notebooks / Notebooks resulted in imported paper having 12-15% cost advantage vis-à-vis paper manufactured in India. After 3 months of market disruption from GST 2.0 reforms, confusions started wading off and market operating prices settled only in Q-IV, though at comparative lower levels than the prices prior to pre-GST 2.0 reforms.
Disrupted supply chains globally due to the tariffs announced by US and the geopolitical situation prevailing in Middle East market continued until Q-III to have adverse impact on Export volumes and realisations. Post US Supreme Court’s decision on US tariffs, stability is restored on Company’s export volumes to US and outlook for this segment is favourable. The escalation of the US–Iran conflict in early 2026, along with disruptions in Strait of Hormuz, hurt pulp shipment reliability and raised freight costs. The global supply chain volatility has resulted in significant increase in the cost of imported pulp, waste paper, chemicals and coal, which is expected to significantly affect the margins in 1st half of FY27.
After difficult first 3 quarters, domestic market sentiments turned favourable in Q-IV with the notebook season, strengthening global pulp and paper prices and depreciation of INR against USD, with last 2 factors making Paper imports in to India costlier. Even though volume pick-up was seen over last 4 months, margins continue to be under pressure.
OUTLOOK:
FY 2026-27 is shaping up to be a year of recovery and reset for the Indian paper industry. After two demanding years marked by margin compression, import surges, and global supply-chain volatility, multiple drivers are converging to support stronger volumes, healthier realisations, and improved profitability-provided policy support holds and global pulp markets stabilise as expected.
Industry forecasters broadly converge on a 6–7% CAGR for paper consumption in FY27. Packaging and paperboard will continue to be the dominant engine, supported by sustained e-commerce growth, rising FMCG penetration, the structural shift away from single-use plastics, and quick-commerce-led demand for corrugated and folding cartons.

1 hour ago
Total Views : 230
2 days ago
Total Views : 1095
last week
Total Views : 3305
last week
Total Views : 2458
last week
Total Views : 733
last week
Total Views : 3399
last week
Total Views : 3397
last week
Total Views : 6727
2 weeks ago
Total Views : 1020
2 weeks ago
Total Views : 930