Join Groups & Channels, No Spamming

Morbi paper mills see full-capacity operations as ceramic industry revives; Kraft paper exports to China spike, Prices strengthen; Janmashtami shutdown ahead
The BE and caustic soda plant marks a key milestone for Mohit Paper Mills, enabling full utilization of installed capacity and enhancing overall production efficiency
Expert Views on the paper market scenario, How the West Asia Crisis Helped the Industry, MIP for WPP, Anti-Subsidy implementation, and paper price trends
Pudumjee Paper intends to develop new varieties addressing applications for stronger paper bags and cupcakes; Plans 68,000 MT Mahad Specialty Paper Facility within 5 years
India Paper Industry at an Inflection Point: War, Costs, and Capacity; Demand growth expected at 5–7% in FY26
“Surging exports of paper will most certainly keep the domestic prices quite high”: Mr. A. Annamalai, Director – RFC
The Status of the Global Container board Industry, Recycled Paper Demand and Supply and its impact on the Indian Industry
Akshay Jain, director of Silverton Pulp & Paper, says it's time to promote agro residue as a raw material to lessen the scarcity of fibre
Advantageously located, a new paper mill is all set to roll kraft paper in Madhya Pradesh
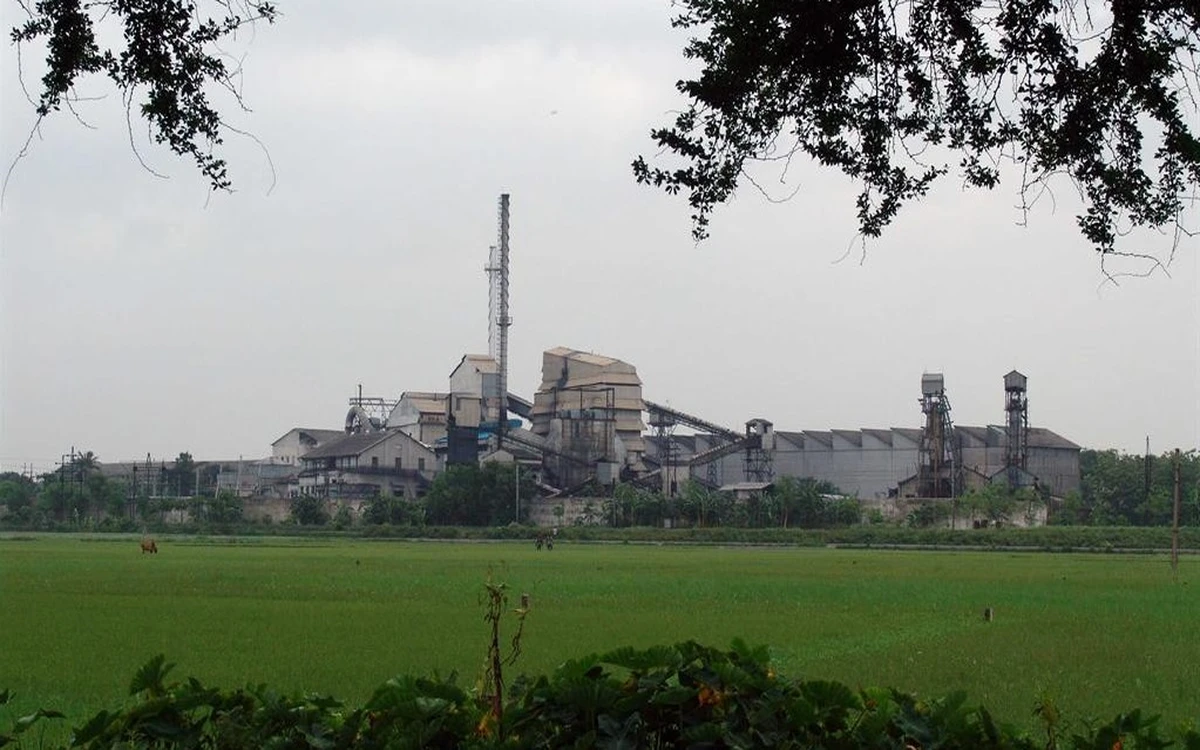
Several agile interventions helped ITC-PSPD fortify its clear leadership of the Value Added Paperboards (VAP) segment
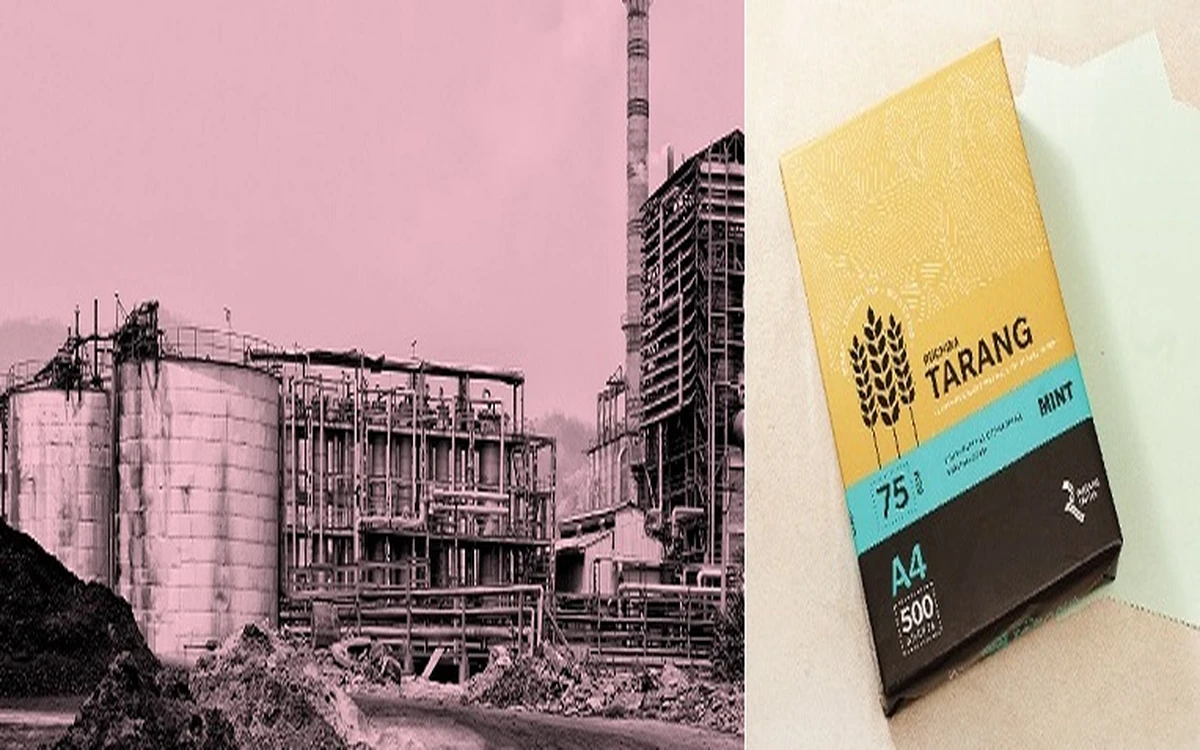
Ruchira Papers Invests a Sizeable Capex of Rs. 235–240 Crore Towards Writing & Printing Paper Capacity Expansion

Paper Price Could Reach Rs. 72,000– Rs. 75,000/Ton in 4–6 Months, Stable Timber Costs, Falling Wheat Straw Prices and Strong Paper Demand Ahead
Paper mills inflated the basic ex-mill price of paper post GST 2.0, AINMA seeks action against Anti-Profiteering
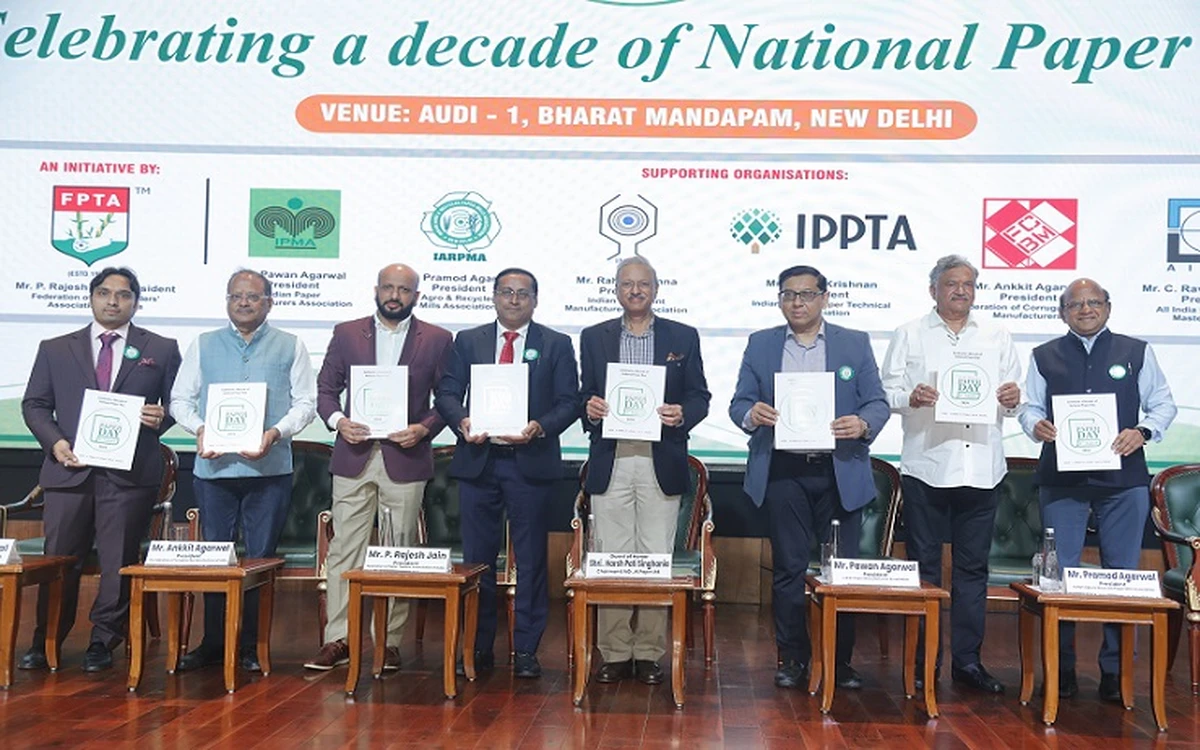
Seven Leading Associations Unite to Celebrate National Paper Day, Highlighting Paper's Sustainability and Circular Economy Advantage
Seven Leading Associations Unite to Celebrate National Paper Day, Highlighting Paper's Sustainability and Circular Economy Advantage
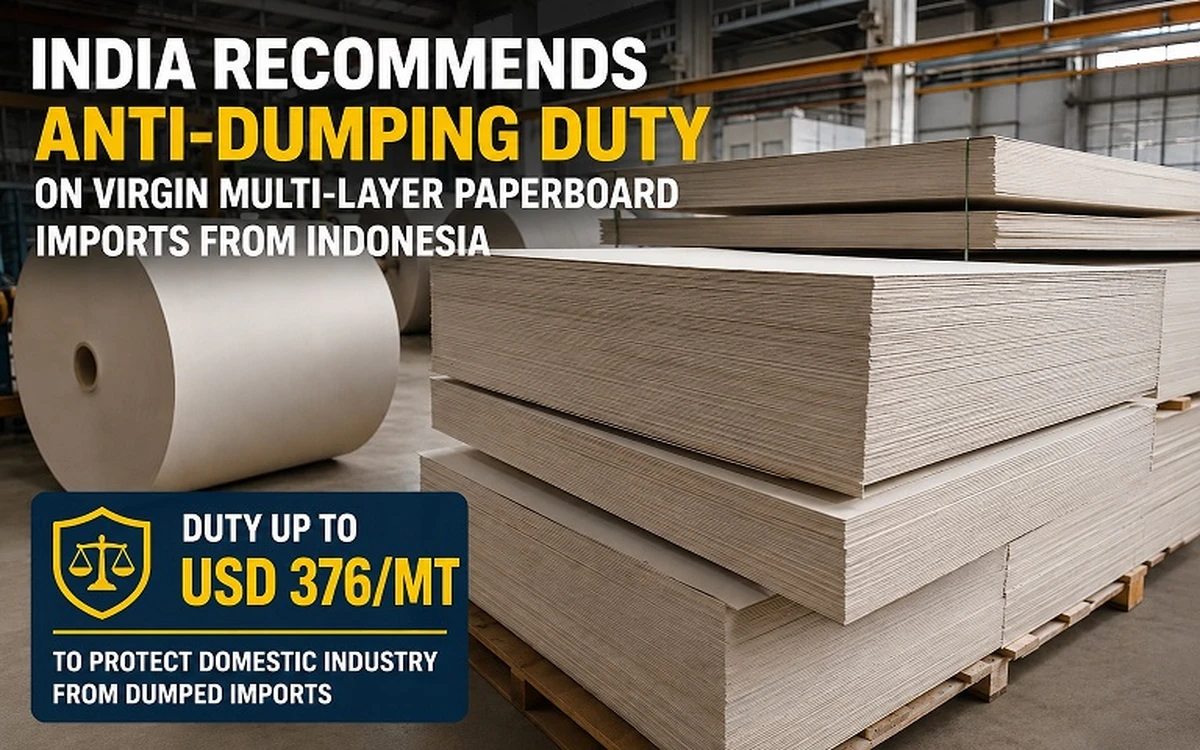
India Recommends Anti-Dumping Duty of Up to USD 376/MT on Virgin Multi-Layer Paperboard Imports from Indonesia
Scientists from IIT-Guwahati develop India's first biodegradable plastic
Navneet Education focuses on brand building, curriculum-led growth, and export recovery; expects stationery margins to improve in FY27
It is estimated that USD10B to USD20B worth of single-use plastic packaging will convert to molded fiber, ZUME
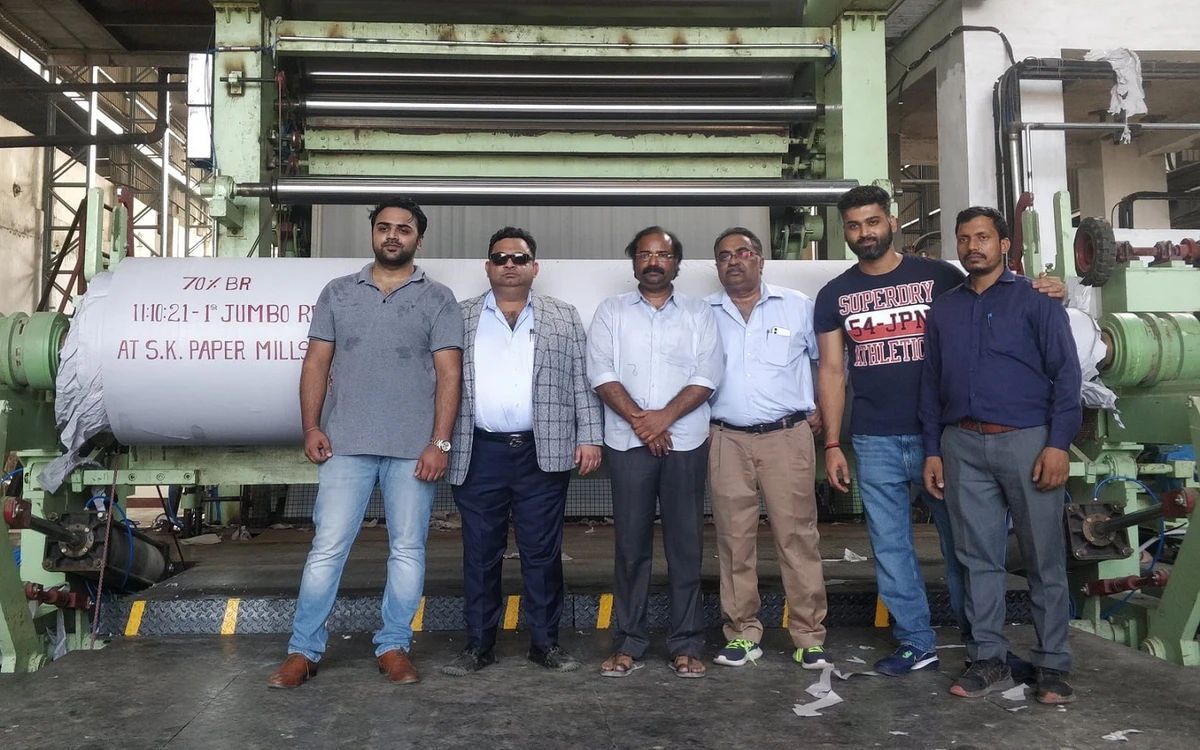
Muzaffarnagar gets a new capacity of Tissue Paper and MG Poster paper
DPIIT Report on the Paper Industry: Recent Expansions & Upgrades, Fastest-Growing Segments, and Total Operational Paper Mills in India
Overview of exports of select type of paper and key raw material used in the industry by Crisil Intelligence
Margin pressure pushes Pulp & Paper Packaging sector toward AI-Driven cost optimization, Cutting costs by 8–20%
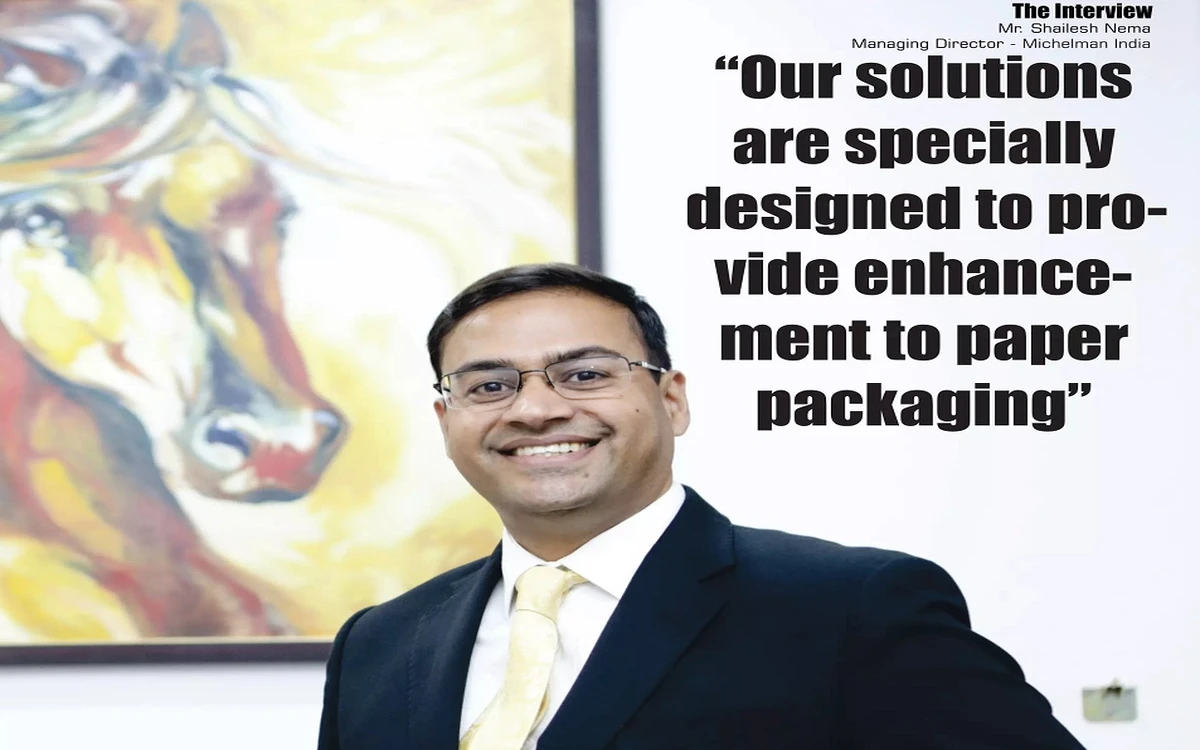
Michelman: Coating Solutions especially moisture and gas barrier on paper significantly improves the shelf life of food
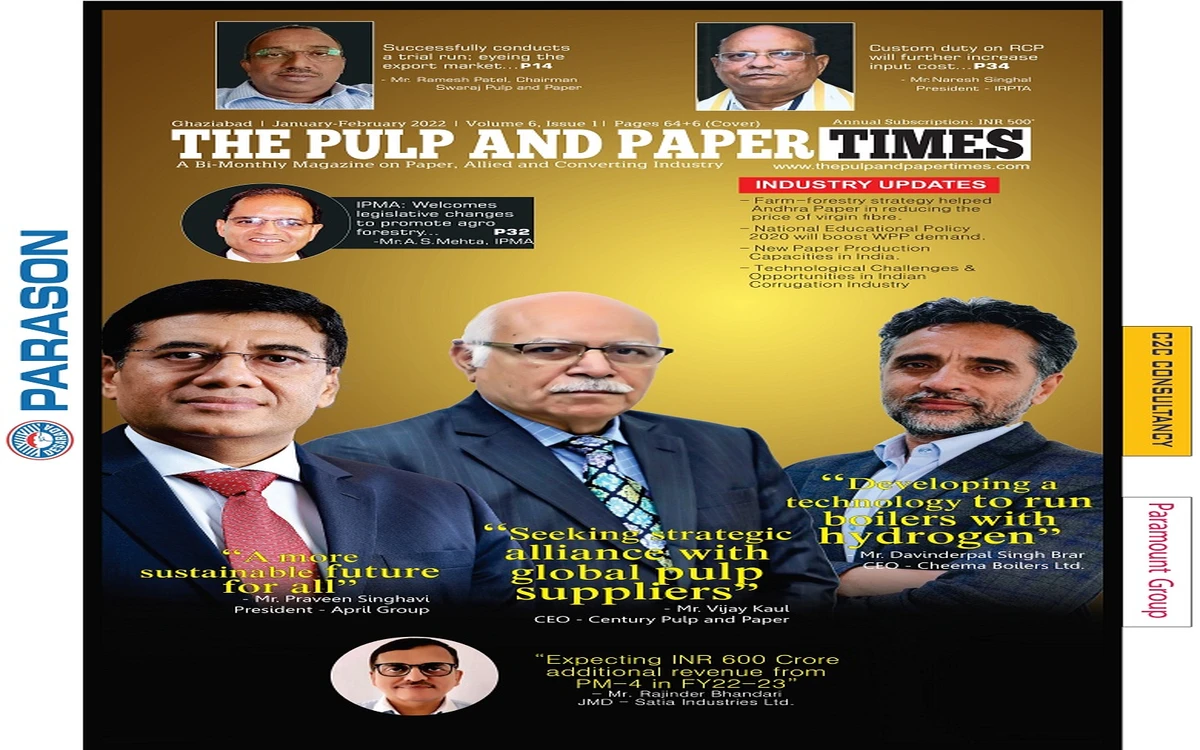
The Pulp and Paper Times Magazine : Volume 6, Issue 1
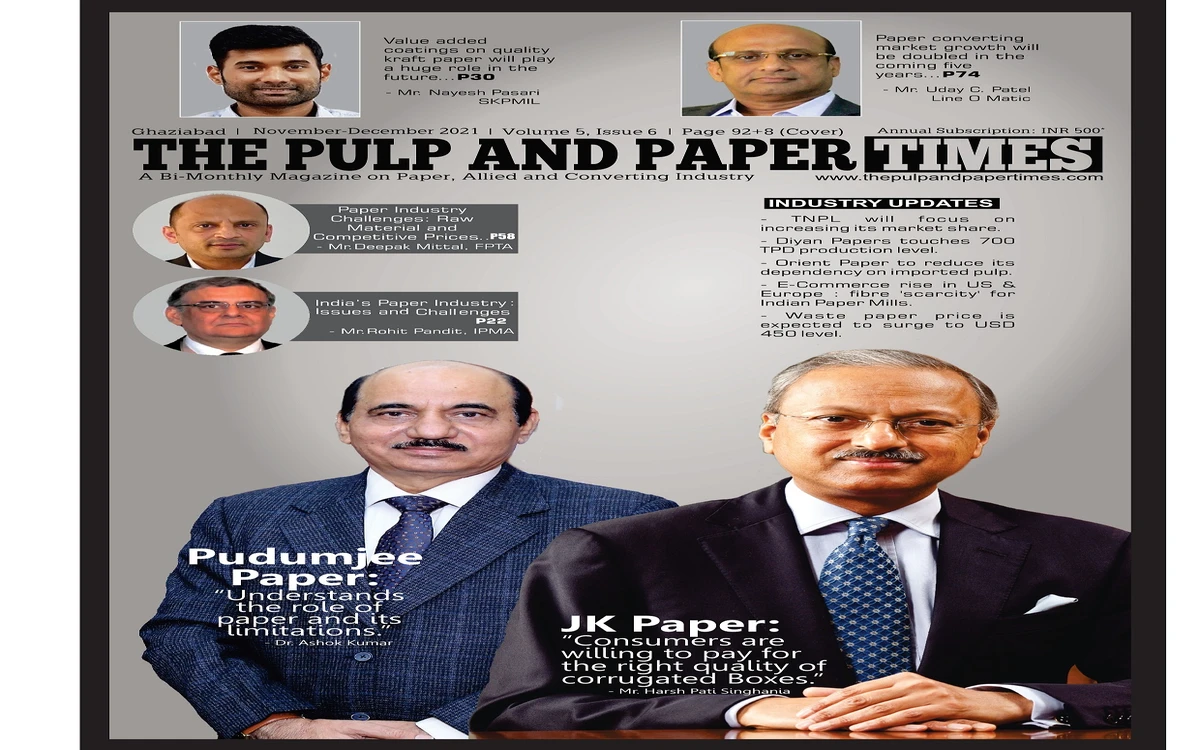
The Pulp and Paper Times Magazine : Volume 5, Issue 6
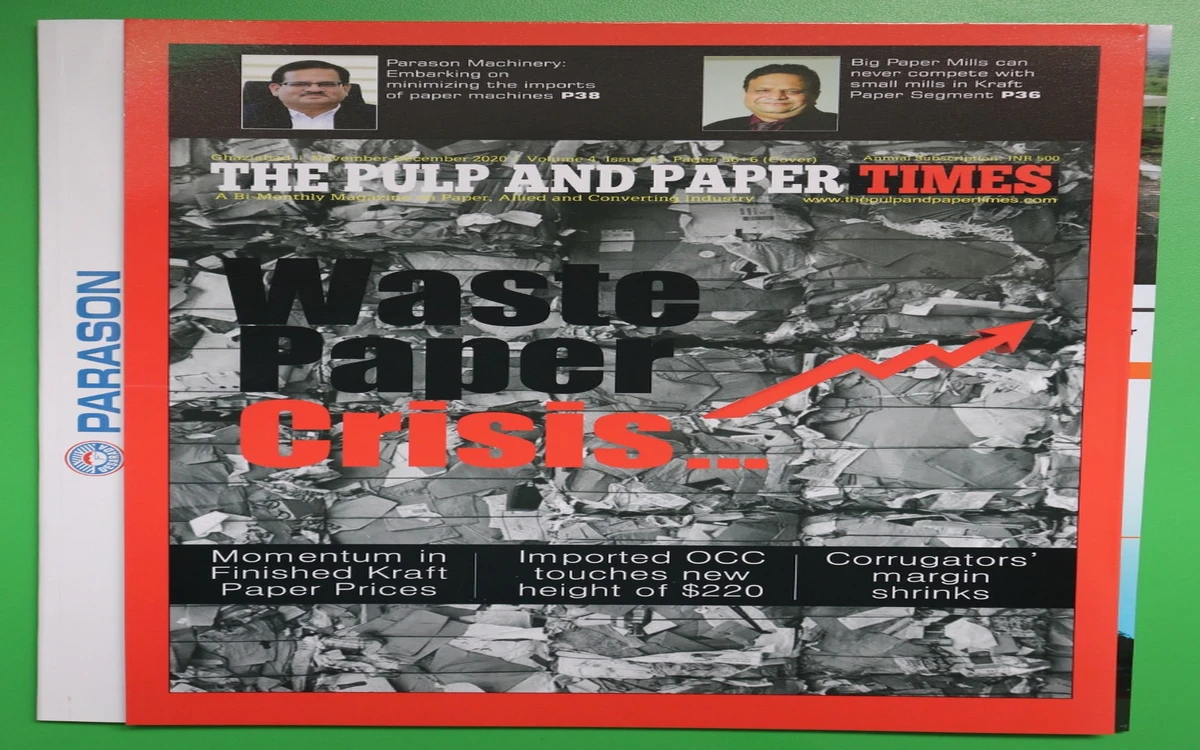
The Pulp and Paper Times: Volume 4, Issue 6
The Pulp and Paper Times : Volume 3, Issue 6
The Pulp and Paper Times: Volume 2 Issue 5
The Pulp and Paper Times, Volume 1, Issue 3
The Pulp and Paper Times, November 2016 Issue
- Acquisition of a second-hand 1,65,000 MTPA paper machine from the USA, and a chlorine dioxide (ClO₂) plant, which is expected to improve operational efficiency.
The Pulp and Paper Times
Ruchira Papers Limited (RPL) manufactures and markets kraft paper and printing & writing paper (WPP), catering to both domestic and international markets. Its manufacturing facility is in Kala Amb, Himachal Pradesh, with a total installed capacity of 1,18,800 MTPA for kraft paper and 60,000 MTPA for WPP, as on March 31, 2026. It also has a captive co-generation power plant of 8.1 MW, catering to the power requirements of its WPP plant.
RPL has a diversified product portfolio comprising kraft paper and WPP. In the WPP plant, the company manufactures a diverse set of products including premium invitation and wedding card paper branded as ‘Mogra’, copier paper, and white paper used for notebooks and stationery applications, cup stock paper, primarily used in the manufacturing of paper cups. It also manufactures industrial grade paper.
According to ICRA Rating, In FY2026, the company’s revenue declined marginally by 1.4% to Rs. 655 crore due to pricing pressures in the WPP segment arising from the continued influx of cheaper imports and a 36-day planned shutdown of the WPP plant in Q3 FY2026 for capacity enhancement and machinery modernisation. RPL’s WPP realisations declined by around 4% YoY and production declined by nearly 3,000 MT YoY in FY2026. Conversely, kraft paper realisations improved by around 2% YoY and the production increased by around 4,000 MT, supported by healthy demand levels.
Enhanced capacity in the WPP segment and continued demand are likely to result in healthy revenue growth for the company in FY2027. RPL’s OPM declined to 12.3% in FY2026 from 16.1% in FY2025, owing to lower WPP realisations, an unfavourable product mix due to the lower contribution from the relatively higher-margin WPP segment, and higher wheat straw costs. Going forward, better product mix, with the likely scaleup in WPP volumes, operating leverage benefits and efficiency gains from modernisation initiatives are expected to support margin recovery.
The company undertook a sizeable debt-funded capex programme of Rs. 235-240 crore during FY2025-FY2026 towards the WPP capacity expansion, acquisition of a second-hand 1,65,000 MTPA paper machine from the USA, and a chlorine dioxide (ClO₂) plant, which is expected to improve operational efficiency. While the acquired paper machine is currently nonoperational, it provides an opportunity for future capacity expansion.
Successful ramp-up of recently enhanced WPP capacity remains crucial for recovery in margins – The company has undertaken significant capacity expansion at its WPP plant, which is expected to increase to 90,000 MTPA over the medium term from 60,000 MT in FY2026. The ramp up in capacity is expected to be gradual to around 72,000 MT in FY2027 and 78,000 MT by FY2028. Healthy utilisation of the enhanced capacity and scale-up of operations, along with an improvement in realisations, remain crucial for growth prospects and margin recovery.

1 hour ago
Total Views : 405
4 days ago
Total Views : 7461
6 days ago
Total Views : 1547
last week
Total Views : 4171
last week
Total Views : 1118
last week
Total Views : 1519
last week
Total Views : 5939
2 weeks ago
Total Views : 2562
2 weeks ago
Total Views : 4518
2 weeks ago
Total Views : 3102